A brand-new limited company can finance a van, even with no trading history. The finance company simply has less to go on, so it looks harder at the people behind the business and at your plans. Here’s what to expect, and how to give yourself the best chance.
Can a new limited company lease a van?
Yes. Every application is decided by the finance company (that’s what “subject to status” means), and a new company usually has to show a little more than an established one. We arrange finance for business customers from a £500 +VAT deposit, on hire purchase or lease, so we see new companies through this regularly.
With no accounts to look at, a finance company will usually want to see some of these:
- Your Companies House registration. Register the company before you apply; the finance company checks who the directors are.
- The directors’ own credit history. When the company has none, the directors’ personal records are what’s left to look at.
- Evidence the payments are affordable. Bank statements, a balance sheet, or contracts and orders already agreed.
- A simple business plan. What the van is for, who your customers are and how it earns its keep. It matters most when the van is what lets you start trading.
A larger deposit can also help an application, because it means less to borrow.
Hire purchase or finance lease?
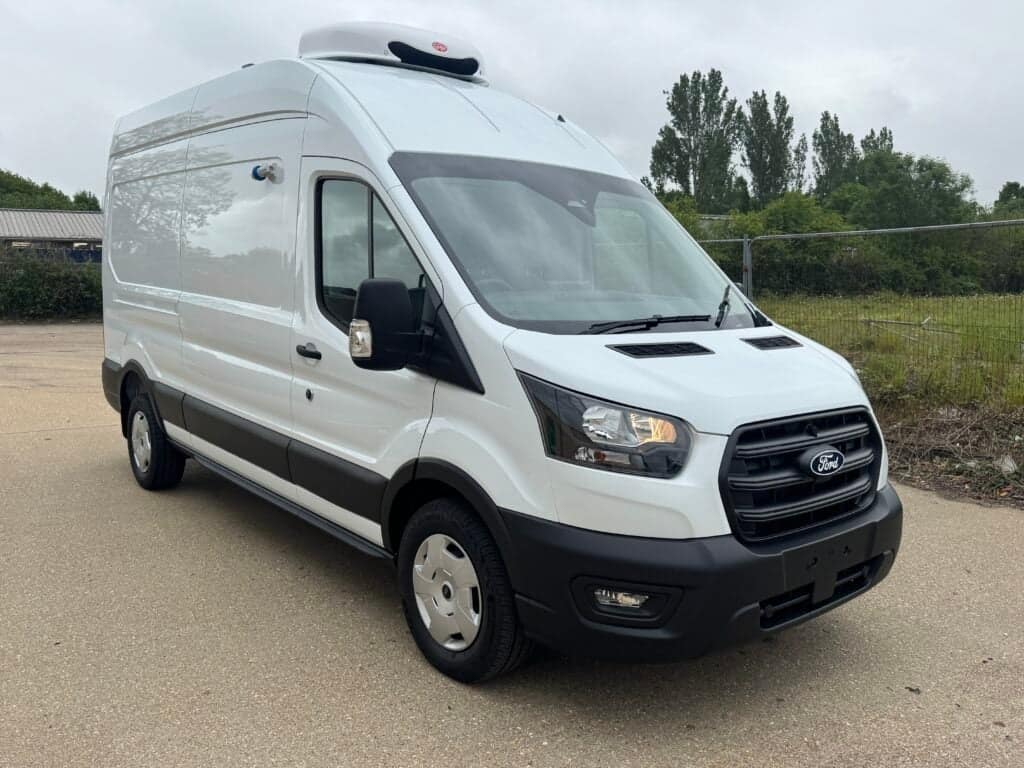
These are the two ways we spread the cost of a new or used fridge van. They suit different businesses, so it’s worth knowing the difference before you apply.
Hire purchase: you own it at the end
- You pay the VAT up front and claim it back in the normal way; there’s no VAT on the monthly payments.
- Payments are fixed at the start, so you know exactly what you’ll pay and when.
- You claim the capital allowances on the van yourself, and you keep all of the money if you sell it later.
Finance lease: you pay to use it
- You pay regular rentals, with VAT on each rental, so less of your money is tied up in the van.
- Finance lease rentals are normally an allowable business expense (your accountant can confirm).
- You look after the van: maintenance, repairs, servicing and insurance are yours.
- At the end you can keep using it for small secondary rentals, or sell it as the lessor’s agent and receive up to 95% of the sale price.
One thing to know: a finance lease doesn’t come with a maintenance package. Servicing, repairs and insurance are your costs, so budget for them alongside the rentals.
Getting ready to apply
- Register the company and open a business bank account before you apply.
- Put your plan on one page: what you’ll carry, for whom, and what it brings in each month.
- Gather anything that proves income is coming: contracts, purchase orders, letters of intent.
- Ask your accountant whether hire purchase or a finance lease suits your tax position better.
- Budget for the deposit and the first payments, plus insurance before the van is delivered.
Choosing the van
Buy for the round you have, not the one you hope to have in three years: a van that’s bigger than you need costs more every month. Our guide to fridge van sizes and new or used will help you narrow it down.
See the vans with monthly figures on our finance page, read how refrigerated van leasing works with us, or browse every fridge van and freezer van in stock. Call us on 01444 245555 and we’ll talk you through it before you apply.